A VA loan offers several benefits for eligible military personnel & veterans when it comes to buying a home.
Buying a home is a huge milestone, and for veterans, active-duty service members, and eligible spouses, a VA home loan can make that goal much more attainable. Backed by the U.S. Department of Veterans Affairs, VA loans offer several benefits designed to help eligible borrowers buy a home with more flexible financing options.
But how do VA home loans work? Who can qualify, and what should you as a home-buyer know about them before starting the home-buying journey? Whether you're purchasing your first home or moving to a new chapter, understanding your VA loan benefits can help you make a more informed decision.
How to Get Started With a VA Home Loan
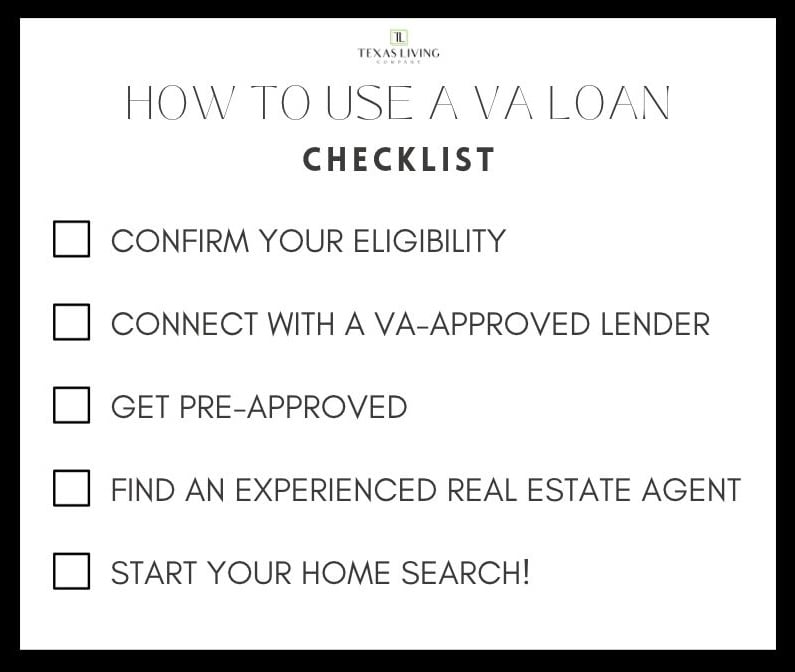
Want to jump right into exploring your VA home loan options and benefits? Here are a few steps to help you get started:
- Confirm your eligibility. Request your Certificate of Eligibility (COE) & learn more about the process through the VA.
- Connect with a VA-approved lender. Discuss your finances, credit, loan options, and estimated monthly payment.
- Get pre-approved. A pre-approval letter from a qualified lender can help establish your budget, make your home search more focused, and create a stronger offer.
- Find an experienced real estate agent. Partner with an agent who understands VA transactions and can help you navigate the homebuying process.
- Start your home search!
What Is a VA Home Loan?
A VA home loan is a mortgage option backed by the U.S. Department of Veterans Affairs. Rather than lending money directly, the VA guarantees a portion of the loan made by an approved private lender. This guarantee helps lenders offer eligible borrowers favorable financing conditions, including special rates (usually lower), better terms, and more.
Besides buying a house, VA loans can also be used to refinance an existing mortgage or make certain home improvements. For buyers, the VA purchase loan is especially popular because it offers benefits that can make homeownership more accessible.
Who Is Eligible for a VA Loan?
VA home loan benefits are available to qualifying veterans, active-duty service members, certain National Guard and reserve-duty members, and eligible surviving spouses.
Eligibility generally depends on your military service history, including the length and type of service. Requirements can vary based on when you served and your specific circumstances. To verify eligibility, borrowers can request a Certificate of Eligibility (COE) through the VA, and should be requested during the pre-approval stage of your real estate journey. This document confirms to lenders that you meet the service requirements for the benefit.
You can learn more or request your certificate directly through the U.S. Department of Veterans Affairs here.
Benefits of Using a VA Loan
One of the biggest advantages of a VA loan is that it can reduce some of the upfront costs associated with buying a home. Here are a few of the benefits eligible borrowers may be able to receive:
1. No Down Payment Required
One of the most well-known VA loan benefits is the ability to purchase a home with no down payment, provided the borrower has sufficient entitlement and the lender approves the loan. This can make a significant difference for buyers who would otherwise need to save thousands of dollars before purchasing a home! While a down payment isn't required in many cases using a VA loan, participating buyers can always choose to make one anyway to reduce their loan balance.
2. No Private Mortgage Insurance (PMI)
Unlike many conventional mortgage programs that require private mortgage insurance when a buyer puts down less than 20% or is a first-time home-buyer, VA loans do not require monthly PMI. This can help eligible buyers keep their monthly mortgage payments relatively low, potentially making more room in their budget for other homeownership expenses.
3. Competitive Interest Rates
VA loans often offer competitive, lower interest rates compared with other mortgage options. However, rates are not fixed and depend on factors such as the lender, market conditions, credit profile, loan terms, and other financial considerations. Comparing offers from multiple VA-approved lenders is a good way to understand your options.
4. No Prepayment Penalty
VA loans do not have a prepayment penalty, meaning borrowers can generally make additional payments toward their principal or pay off their mortgage early without being charged a penalty for doing so. Unfortunately, many traditional home loans do enact a prepayment penalty.
5. Multiple Use Benefits
Luckily, VA loans can be used more than once, depending on a buyer’s eligibility. Usually, an eligible borrower is approved for a certain amount of funds, so can use a VA loan again if they are below that limit. In some situations, veterans can even have more than one VA loan at a time!
VA-backed loans may also be assumable, meaning a qualified buyer may be able to take over an existing VA loan, subject to lender and VA approval. This can be an attractive feature if the existing mortgage has a favorable interest rate.
What Is the VA Funding Fee?
While VA loans offer several cost-saving benefits, most borrowers are required to pay a one-time VA funding fee. This fee helps support the VA loan program and reduces the cost to taxpayers.
This funding fee is not static and the amount depends on factors such as:
- Whether this is your first time using a VA loan or not
- The size of your down payment, if any
- The type of loan you're obtaining
For purchase loans, the funding fee may be financed into the mortgage rather than paid entirely at closing. Some borrowers are exempt, including eligible veterans receiving VA compensation for a service-connected disability and certain other qualifying individuals. Because this fee can vary from situation to situation, it's important to ask your lender to explain how much you'll owe and whether you qualify for an exemption.
What Types of Properties Can You Buy With a VA Home Loan?
VA home loans can be used to buy several types of residential properties, provided the property meets VA requirements and will be used as the borrower's primary residence.
Eligible property types may include:
- Single-family homes
- Multi-unit properties
- VA-approved condos
- Manufactured homes
- New construction
It's important to remember that VA loans are intended to help service members own their primary residences… so, it’s not typically approved for vacation homes or investment properties. Your lender can help determine whether a specific property meets the program's requirements.
VA Loan Appraisal & Home Inspection Process
If you're purchasing a home using a VA loan, the property will need to undergo a VA appraisal. Similar to a standard appraisal, this appraisal serves two important purposes: determining the home's reasonable value and checking that it meets the VA's Minimum Property Requirements (MPRs). These requirements help ensure the property is safe, structurally sound, and sanitary for the buyer. If the appraisal identifies any issues that need to be addressed, they’ll have to be resolved before the loan can close.
An appraisal is not the same as a home inspection. While an appraisal evaluates the property's value and basic condition, a home inspection provides a more detailed look at the home's systems and components, such as the roof, plumbing, electrical, and HVAC systems. And while the home inspection is usually optional, the appraisal is not.
Our strong recommendation: Buyers should always schedule an independent home inspection. Knowing about potential repairs or maintenance concerns before closing can help you make a more confident decision!
Can Sellers Deny VA Loan Offers?
Yes, a home seller has no obligation to accept a VA loan offer. And unfortunately, it’s not uncommon for a seller to outright bar VA loans due to their more rigid appraisal requirements. Also, there are more rules and regulations when it comes to seller concessions and buyer incentives. For sellers, understanding the basics of VA financing can help make the transaction smoother and avoid any misconceptions about accepting a VA-backed offer.
For those considering homeownership, a VA loan can be an excellent way to make the dream of owning a home a reality. And understanding how your benefits work is the first step toward making the most of them.
At Texas Living Company, we are so grateful to the veterans, active-duty service members, and military families who have sacrificed so much in service to our country. So, we're proud to help Houston-area military buyers navigate their real estate journeys. If you're a veteran or military family thinking about buying a home, we'd love to help you explore your options and find a place to call home. Contact us today!
Thank you for your service!
Publishing note: This article is educational and not a substitute for individual mortgage, tax, or legal advice. VA loan requirements and lender guidelines can change, so buyers should confirm current eligibility and loan terms with the VA and a qualified lender.

Alexis Feezel is a results-oriented Marketing Coordinator responsible for developing, implementing, and overseeing all promotional strategies and activities to effectively market clients & listings and maximize sales.